
Behind the Yield
Life support: The math doesn't work
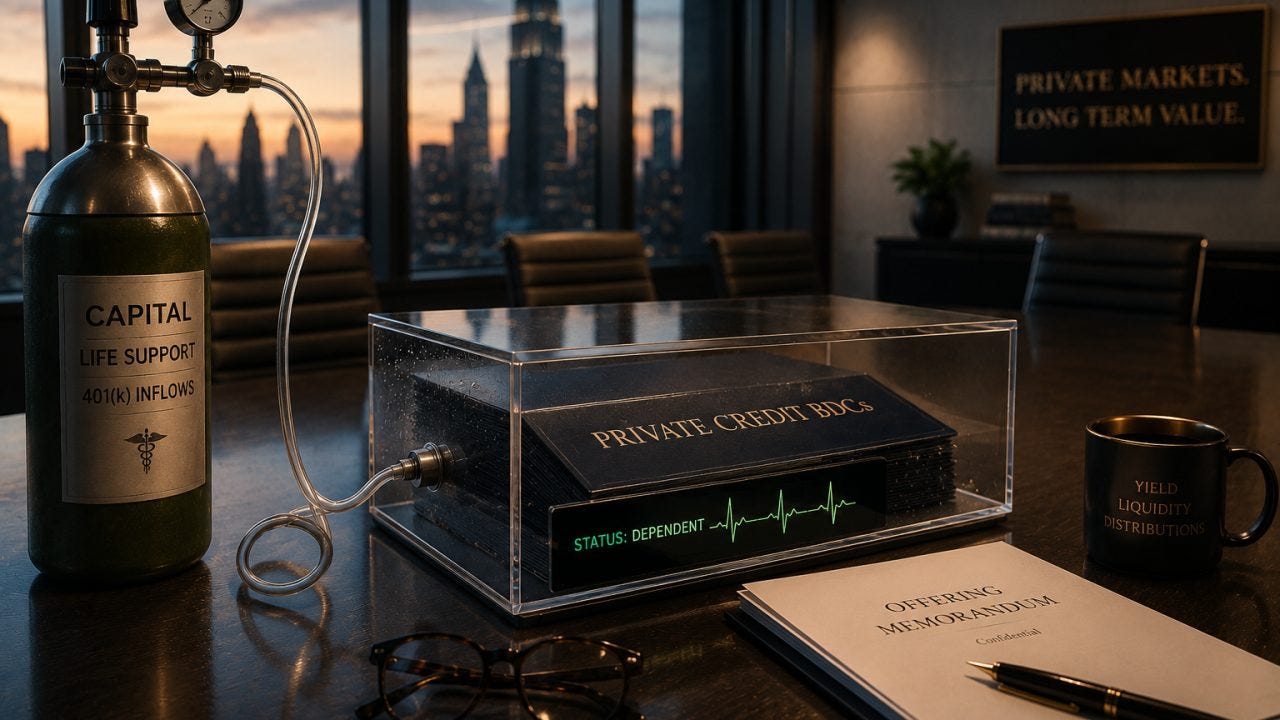
Nobody saw it coming. Or everyone did and nobody said it.
For ten years, they sold a product with the promise of BDCs, quarterly redemptions, and manager fees at 2% per year with 20% on the upside. Advisors showed investors the prospectus. Compliance teams gave their okay. Investors collected the returns without understanding why the math only worked if one thing didn't happen: if people tried to get their money back.
Then Q1 2026 happened.
$7 billion of investors wanted out of private credit BDCs. Yet only $5 billion came in. For the first time in ten years, outflows beat inflows.
Someone did the math. They realized that the company built an entity that only worked when people didn't try to get their money back.
They tried to get their money back. The machine broke. They all went to the prospectus for answers.
BDCs invoked their caps, gates, and queues. Blackstone had to inject $400 million into their fund to meet redemptions. Blue Owl rejected offers to redeem their shares. Ares asked for 11.6% of investors' money and only gave 5%. BlackRock's HLEND asked for 9.3% and only promised 5% to investors. Everyone else could have a number in a line.
The guy who operated the credit machine for Apollo said, "I literally think all the marks are wrong."
The operator of the system admitted the system was lying.
The valuations were fiction. The returns were fiction. The only thing that wasn't fiction was the 2% fee the sponsor pulled every year while the BDC functioned.
When the BDC broke, the sponsor didn't break with it. They collected the fees for ten years while the BDC lied to investors. They control the BDC's valuation. They absorb zero of the loss.
The advisors didn't absorb the loss either. They showed investors the prospectus. Compliance stamped it with their approval. Advisors will point investors to the prospectus when they ask why their shares are in a redemption queue.
The platforms, wealth advisors who created the systems for these BDCs to function don't absorb the loss. They sold the products. They created the systems. The BDCs work for someone else now.
Institutional investors, especially LPs, understand liquidity conditional on investors asking for it. They have other capital. When their shares are in a queue, they move their money elsewhere. They absorb the loss and keep going.
Yet someone understood from Q1 2026 what happened in the industry. Maybe the sponsor. Maybe a platform executive. Maybe a regulator trying to solve a different problem. The structure was broken. It always would be when redemption requests hit such high numbers. Yet it didn't have to break if the entity was fed the right kind of capital.
The kind that doesn't ask for its money back when there's stress in the market. The kind trapped in 401(k)s and IRAs. The kind that comes with a captive audience of individuals who have no other place to put their money.
On March 30, 2026, the Department of Labor proposed opening up $12.4 trillion in retirement accounts to private credit BDCs and interval funds.
This was no accident.
The sponsor of the BDC had a math problem and needed a patient to absorb the loss. The 62-year-old woman looking for yield would be perfect. She'd read the offering circular and believe that quarterly redemptions would happen every quarter. She wouldn't know about the gates. She wouldn't understand that the moment redemption requests overtook share offerings again, she'd be holding a product that promised redemptions yet had a gate locked.
Because gates will spike again. This is what gates do. The math doesn't change when gates are invoked.
The sponsor didn't work to fix the structure. They just found a category of investor who didn't know they were in a queue for their money.
Advisors didn't object to the structure of the BDC. The product is compliant. The prospectus is clear. If one of these retirees calls and asks why her quarterly redemption is in queue 47, the advisor has the prospectus to prove where they got their information.
The platforms didn't blink. These entities have the infrastructure in place. They've created the systems for these BDCs to operate and take the AUMs they do. More shares means more basis points for the sponsors.
Regulators say the industry is democratizing access to investment alternatives.
Call it what it is: moving the math that doesn't work for BDCs to the people who can't afford to lose their money to such a failure.
Here's the proof that the BDC will break on them again. The math behind BDCs only works when inflows beat outflows. In Q1 2026, the outflows beat the inflows. Sponsors invoked the prospectus but did nothing to fix the problem. They didn't lower the fees they collect from BDCs. They didn't change the structure of the BDCs. All they had to do was for the inflows to start to beat the outflows again.
Retirement accounts will provide that. Patient capital doesn't ask for the shares in BDCs until they have to. They can't move their money fast enough to get out of these shares before the next problem comes along.
A woman who's 62 years of age who has $500,000 in a BDC and who needs the money for medical expenses in year three has no other capital. She only has what she's put into her 401(k) and her checking account. When the gate closes on her shares and she's in a queue, she'll call her advisor and the BDC sponsor. She'll have to sit through the process of waiting for her shares to be redeemed.
The math that doesn't work for BDCs and the one that only ever works if nobody ever tests the gates on these BDCs finally proves itself in her life.
The BDC structure may be broken but it's working as it was designed for everyone except her.
You can't fix a machine by changing who operates it.
There's no doubt the math doesn't work for BDCs. Sponsors saw it fail in the first quarter of 2026. They all went to the prospectus and invoked the gates on their BDCs. The industry saw that the original premise that money will always come in one of these BDCs is a fantasy.
All they did was find a source of capital that can't leave.
They called it access.
Get Behind the Yield free by email. Short enough to read before your first meeting, specific enough to use in it. Subscribe here.
Need CE hours? Six self-study bond courses, accepted by CFP Board. See the courses.