
Bond Math for Advisors
Online
Course
2 Modules
Can be accessed via desktop or mobile devices
$ 19
Why this course
Built for CFP® professionals, RIAs and wealth advisors.
Every bond conversation sits on a few pieces of math. Why the price fell when rates rose. Which yield to quote. How much a client’s bonds could lose if rates jump 1%. Most advisors know the terms. Fewer can run the numbers in front of a client.
This course works through that math step by step, with worked examples and calculators. Each lesson starts from a question clients ask, runs the numbers, and ends with how to say it in plain language. The examples are built for teaching, not tied to today’s market, so the course holds up whenever you take it.
Who it's for
- Advisors who want to quote the right yield on a client statement
- Planners who want to size a client’s rate risk in dollars, not just percent
- Advisors whose clients own callable bonds or premium bonds
- CFP® professionals who want CE credit on something they'll use the next week
The course
- Format
- Online, self-paced
- Modules
- 2 modules
- CE
- 1.0 hour
CFP Board accepted, Program ID 354946 - Devices
- Desktop or mobile
- Price
- $19
Open to all advisors. CFP Board CE credit for CFP professionals.
How your CE credit works. Enter your CFP Board ID when you start. Work through the two modules in order, watch each module video and pass each module quiz, then complete a short evaluation and download your certificate. We report your 1.0 hour to CFP Board within 14 days.
Want to look inside first? Take a free look inside →
What you'll learn
2 modules · self-paced
01
Price, yield and return
Why price and yield move in opposite directions, which yield to quote (current, to maturity, to call or to worst), where a year’s return comes from, and how far rates can rise before a bond loses money over 12 months.
02
Duration and convexity
Macaulay and modified duration, DV01 in dollars, a portfolio’s duration, why duration misses on big rate moves, and why callable bonds act differently when rates fall.
The 4 sources of a bond's return
A 2-minute lesson from the course. More short lessons on YouTube.
Free weekly note
Not ready for the full course? Start with the Rate Desk Note.
One page every Monday on where the Fed, the Treasury curve, munis, credit and money fund cash stand, and what each one means for a client buying bonds.
A new note every Monday morning. No spam, unsubscribe anytime.
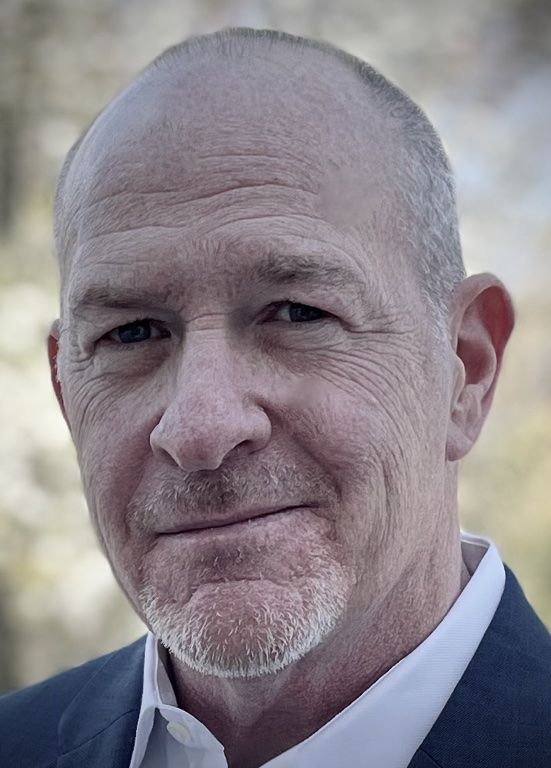
Your instructor
Charles Urquhart, CFA
I've worked in the bond business since 1990. I started at Lehman Brothers in the fixed income rotational sales and trading program and became VP, institutional fixed income. I then spent 18 years at Fidelity Capital Markets running sales and coverage for individual fixed income securities across the retail, correspondent, RIA and family office channels.
After that I moved into fixed income technology, running the New England region for Tradeweb Direct and working with institutional investors at Andrew Davidson & Co. Today I teach FI 380, Fixed Income Securities, at Loyola University Maryland and train advisors through Fixed Income Resources.
Nobody sponsors this course. There's no product pitch at the end.
Part of The Bond Series for Advisors
Compare all six, or get all six for $99 →Six self-study courses sized to the CE hours you need. Take one, or work through the series.
Course 1 of 6 · 1.0 CE hour
Building & Communicating Bond Ladders for Clients
Course 2 of 6 · 2.0 CE hours
Explaining Bonds to Clients
Course 3 of 6 · 4.0 CE hours
Individual Bonds for Advisors
Course 4 of 6 · 2.0 CE hours
Munis for Advisors
Course 5 of 6 · 1.0 CE hour
Bond Math for Advisors
Course 6 of 6 · 2.0 CE hours (from 2027)
Is the Extra Yield Worth It?