
Behind the Yield
The Case for the Nest
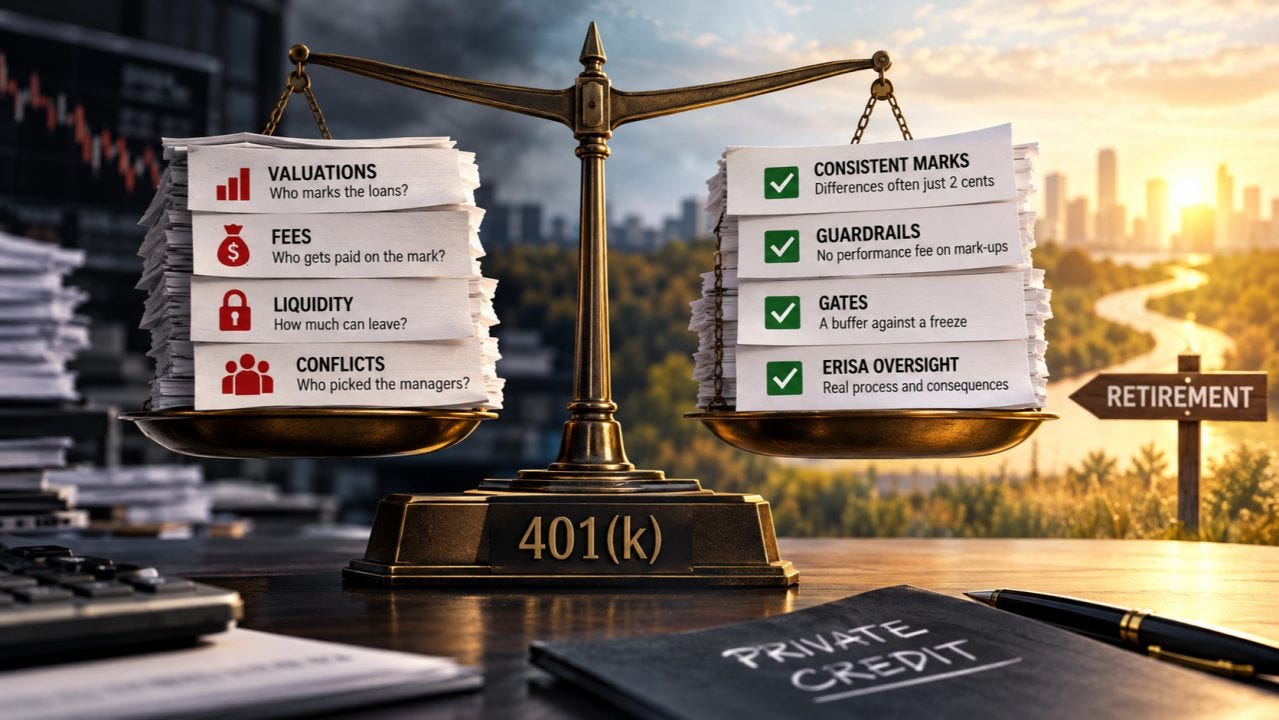
My post last week on private credit in your client’s 401(k) attracted a sizable number of people. Some were nice. Some were not so nice. Most said the same thing. Chuck only argues one side.
It’s tough to argue with that. I’ve been in bonds since 1990. We can see both sides on every transaction, assuming our side is the one that is compensated.
This week I did something different for me. I asked the people who like private credit to give me their best answers to my four questions. No sales literature. Just research.
Here is the scoreboard.
WHO MARKS THE LOANS?
Private credit loans are not traded. Therefore, the value of the loan is assigned by the fund owning the loan. Accountants call this Level 3. I’ve always called this the honor system but in a nicer font.
This summer, Alexandra Dogaru of Berkeley tested this claim. Large private loans get split up, so the same loan lands on several BDC books in the same quarter. She lined those marks up side by side. She tested 110 BDCs.
These 110 funds generated 97,092 marks on 8,730 loans from late 2022 to early 2026.
For a typical loan, the difference between the maximum mark and the minimum mark was 0.02 points.
Two cents for a $100 bond. I’ve seen bigger disputes over who gets the last donut.
For the majority of loans, most of the time, these values were the same. This was not something I expected. Point to the other side.
However, when loans go bad, differences between marks exist. Once the average mark was below 95, the percentage of loans with more than five point differences between max and min marks increased from 6% to 17%.
She also found something else. Funds that generate more of their income from PIK marked the same loan slightly higher than the other funds. PIK means that interest payments are made by increasing the size of the loan. A good example of PIK is using your Mastercard to pay for your Visa bill. The difference in marks was about a quarter point. When a fund was subject to an audit in a quarter, the difference was not present. Amazing what a little oversight can do.
Call it for the other side on the average loan. The fight is over the ones going bad.
WHO GETS PAID ON THE MARK?
I had this one in the win column before I began the post. Oops.
The law says a BDC manager cannot charge a performance fee on a mark-up. The capital gains fee is capped at 20% of the realized capital gain. Paper losses are subtracted first. A mark-up on a loan results in the capital gains fee remaining the same. A mark-down on a loan results in the capital gains fee decreasing.
Of the 132 BDCs in Dogaru’s analysis, 95 indicated that this is the case in their filings. Some funds go a step further and look back 12 quarters before paying the income fee. If NAV falls, the manager can lose a fee it was planning to spend.
I bet that the majority of advisors have not read this deep in a fee table. I do not blame them. This looks more like a refinery manual.
However, the fee table does not end here. There is a management fee that is charged based on assets. In addition, 126 of the 132 BDCs include PIK interest in their performance fee calculation. The performance fee is paid quarterly even if there is no cash received.
Call it for the other side. The law pulls its weight here.
HOW MUCH CAN LEAVE, AND WHO DECIDES?
This is the best round for the other side. They won this one with a story.
In December of 2015, I was on the retail bond side at Fidelity when Third Avenue’s Focused Credit Fund froze. This was a $788.5 million high yield mutual fund that allowed redemption at any time. The bonds inside it didn’t sell any day. Some of them barely sold any season.
Money had been leaking out of the fund all year. On December 10, Third Avenue halted all redemptions.
When the SEC approved the freeze, it laid out the alternative. Without it, institutional investors would leave first. Retail investors would receive what was left.
A 5% quarterly gate stops this from happening. This is akin to the line at the airport. None of us enjoy this. All of us board.
And the line is getting shorter. Fitch tracks 15 perpetual non-traded BDCs. At 13 of these funds, Q3 redemption requests averaged 9.8% of shares as compared to 10.8% in the previous quarter. At six funds, requests were less than 5%. According to Fitch, a lot of the remaining requests come from the same people getting back in line.
However, there is one paper that spoils the mood. In June, Chuck Fang, Itay Goldstein, and Yao Zeng published a paper through NBER. Cash on hand and loan repayments are insufficient to cover 5% of redemptions at every quarter for a long period of time. New money goes quiet just as redemptions start to increase. Therefore, funds sell loans, borrow more, or pay investors late. Investors that remain bear the cost.
Call this for the other side. A gate is better than a freeze and I experienced a freeze.
WHO PICKED THE MANAGERS, AND WHO OWNS THE FIRM THAT PICKED THEM?
The other side answers with one word. ERISA.
Putting a lemon on a menu for a 401(k) creates a situation where the fiduciary may be personally liable. The idea of their own name appearing in a court filing is a great way to focus a plan sponsor.
This morning I read a CFA Institute article by David Blanchett and Spencer Look. They examined 401(k) menus over ten years.
Core funds’ fees decreased from 0.69% in 2013 to 0.39% in 2023.
Active funds’ fees decreased from 0.75% to 0.52%.
Small plans pretty much closed the gap with the big ones.
This is a system that works. The trustees bringing private markets into 401(k) plans have retained control of the final fiduciary decision. The ownership stakes are right there in public filings.
Call this for the other side. Real process and real consequences.
WHERE I COME OUT
So there is their case, hair combed and shoes shined. Most marks agree. The law blocks a performance fee on a mark-up. The gate is there for a reason I watched firsthand. 401(k) fund fees have decreased by more than 40% over the last ten years.
I entered this post believing that I would sweep. However, I lost all rounds.
I still do not believe that private credit belongs in a target-date fund.
Now take a look at their answers. All of these answers are about the fund. None of these answers are about who gets paid between the fund and the investor.
The manager values a loan and charges a fee based on the value it places on the loan. PIK allows the performance fee to be earned on interest that is still an IOU. The bump in the marks lasts until the auditor shows up, and the auditor shows up once a year. New money buys in at NAV every month.
The gate protects the fund but does not touch the sale. The S shares of Blackstone’s flagship credit fund have an upfront fee of up to 3.5% and a servicing fee of 0.85% per year for the duration of the client’s ownership. On a bond desk, nobody would leave 3.5% on the table. Here, it is captured on the way in. The gate only matters on the way out.
Ares’ big non-traded credit fund earned $735 million in net investment income during 2025. It distributed $816 million. In the same year, approximately $5.3 billion of new money flowed into the fund. Funds such as this require new investors the way a shark needs to keep swimming.
Great Gray is a $371.8 billion retirement trustee. Great Gray hired iCapital to help evaluate and recommend its private markets managers. iCapital is part-owned by managers it could recommend. BlackRock alone owns about 21% according to BlackRock’s own filing. This is not an accusation. This is an org chart.
Now put all of this in a target-date fund.
Very few people actually choose their target-date fund. It is the default. Your money goes to your target-date fund if you leave the enrollment form blank. There is no advisor. There are no questions about gates. Payroll sends money every two weeks like clockwork. If your fund is like a shark, you have an ocean full of fish.
Great Gray’s private markets target-date fund costs between 26 and 46 basis points total. A target-date fund using an index costs about 3.
And what do investors get for the extra cost? New direct loans today pay under 100 basis points over syndicated loans. On 2017 and 2018 loans it was over 300 basis points. Lockups today pay about a third of what they used to pay. And that is when the industry decided retirees can’t live without private credit. Where I come from, this is buying the top.
Finally, there is one piece from the CFA study. The researchers left out target-date funds because the data was insufficient. The part of the menu that could not be measured is exactly where private credit is headed.
Liquidity is the risk everybody already knows. It is on page one. Conflicts appear on page forty, next to the part nobody reads.
Private credit can work for an investor who chooses it with their eyes open. A target-date fund is built for the investor who never picks anything.
Same hill. Still not moving.
Which answer moved you? Let me know in the comments.
Get Behind the Yield free by email. Short enough to read before your first meeting, specific enough to use in it. Subscribe here.
Need CE hours? Six self-study bond courses, accepted by CFP Board. See the courses.