
Behind the Yield
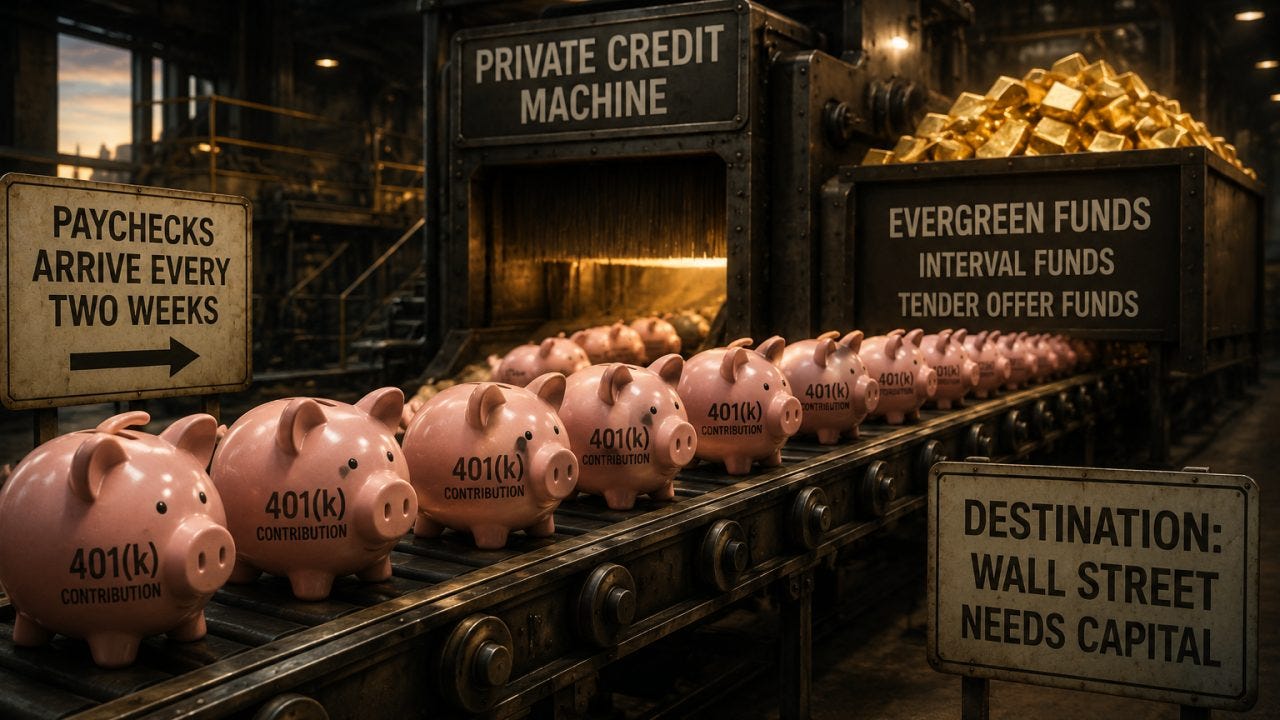
Your 401(k) Is the Solution to Someone Else's Capital Problem
Quick question.
When was the last time you heard someone say, “I wish my 401(k) had more exposure to loans that don’t trade”?
Take your time thinking about it. I’ll wait.
No one has ever said it. Not once in the history of Americans talking about their money. Yet the world’s largest asset managers have spent the last eighteen months creating investment products for a demand that does not exist. So either every product committee on Wall Street hallucinated the same customer at the same time, or someone promised to deliver one.
Someone promised to deliver.
In 2025, 67 new interval and tender offer funds launched. In 2024, there were 49.
The number of evergreen private market funds launched hit a decade high in 2025: 123 private funds were launched, 49 of which were in the private debt space.
Evergreen private debt funds passed $644 billion by June 30, 2025, a 28% increase from the end of 2024.
Six months. Twenty-eight percent.
Tulips grew slower.
In 2026, the industry didn’t take a breath. Eight interval funds launched in the first quarter of the year alone.
Hamilton Lane launched two new funds: one focused on private credit and the other on infrastructure.
Fidelity filed to launch its Private Credit Company II.
Somewhere on the planet, a committee of investment managers approved a sequel to a movie that no one saw on the silver screen.
AB filed to launch its Tax-Aware Credit Opportunities Fund.
Blue Owl raised $850 million upon the debut of its interval fund in September 2025, one of the largest launches in the history of the product class.
T. Rowe Price and Goldman Sachs are developing a public-private equity fund together.
Six more funds were filed for in April.
Another four in May.
Then in July, Wellington, Vanguard, and Blackstone launched their evergreen private investment funds.
Either this was the greatest outbreak of synchronized thinking in the history of Wall Street, or all of them read the same memo.
Take a look at Vanguard, for example.
Jack Bogle spent fifty years telling your grandmother that the best way to invest was to purchase the market at three basis points and live the life that she enjoyed after retirement.
Now, Vanguard is teaming up with the world’s largest alternative asset manager and Wellington’s $1.3 trillion Boston partnership to offer exposure to private investments whose underlying assets do not trade at all.
I don’t know what Jack Bogle would think of all this.
Whatever it is, it is not printable.
In total, there have been sixty-plus interval and tender offer fund launches this past year alone.
Nine of the biggest firms in American asset management delivered funds with the same offerings in the span of four months.
For customers who have never heard of them.
What could possibly explain this?
Funny you should ask.
In August 2025, the White House issued an executive order directing the Department of Labor to investigate opening the nation’s 401(k) plans to private market funds.
In March 2026, the Department of Labor proposed a safe harbor for 401(k) plan fiduciaries who chose to invest in alternative funds.
From April until July 2026, the nine industry giants launched their evergreen private funds.
What a coincidence.
You know what we called coincidences like this on the desk at the office?
A calendar.
Now, the part that was never reported in the press releases.
Evergreen funds offer two main promises to investors: income from the initial investment and the promise of liquidity every quarter or every month for the investor’s money.
Lovely promises.
Yet the funds consist of private loans that do not trade.
Where does the promised liquidity come from for these funds?
From you. And from the next you.
The fund pays anyone who leaves the fund using the capital from individuals who have just joined the fund.
As long as the number of individuals who join the fund exceeds the number who leave, the fund can meet its promises regarding liquidity. When the number of investors leaving the fund is greater than the number joining, the fund manager faces three options: sell the underlying private loans for their real market value, borrow against the value of the fund, or gate the fund.
One option reveals the truth about the value of the underlying investments.
Another borrows against the fund’s value.
The third locks its doors on the investors who seek to leave the fund.
Guess which one is the industry favorite.
The flow has started to reverse for these evergreen private fund managers. Pensions and endowments have reached their targets for how much money they will invest in these funds. A few family offices have started actually examining the valuations of the companies taking the loans. Insurance regulators are beginning to express concern over the amount of illiquid private debt building up on insurers’ balance sheets.
The nine-figure checks that built this industry have begun to arrive later and with less money in them.
June 3, 2026 marked the day when the private investment fund manager Partners Group gated its $8.6 billion Global Value SICAV fund.
Investors had requested redemptions equal to 9.8% to 10% of the fund’s NAV in the second quarter.
The fund permitted redemptions of only 5% of NAV.
Investors who did get money out received only 62 cents on the dollar that they requested.
The remaining 38% of the redemption requests were canceled.
These are some of the wealthiest individuals in the world.
They asked for their money.
They did not receive it.
Partners Group stock fell 17% on the day of the announcement, its worst single-day drop in more than two decades. Blackstone stock fell. KKR fell. Ares fell. None of these companies had gated any of their funds.
The market was not grading one company’s failed effort to create liquidity for its investors. It was grading the entire industry’s business model.
The marketing departments for these companies continue to insist that all is well. The tape does not perform investor relations.
Blue Owl felt the redemption pressure too. Its OBDC II tender cleared at a price 33% lower than its NAV.
Not three.
Thirty-three.
Those who left took one-third less than the value printed on their statements.
Evergreen private fund managers have only one answer for investors who begin to request the return of their investments: returns have been solid, and the gates have worked as they were designed to.
Both true.
But the design of the gate creates a precondition for the success of the fund: there should never be a shortage of new money to invest in these funds.
The new money has stopped.
Which brings evergreen private fund managers to their next concern.
Where do they turn when the money stops coming in?
To Washington, D.C.
It always goes to Washington, D.C.
The Department of Labor has proposed a regulation that would allow these funds into 401(k) plans holding $14 trillion in assets.
That is not nearly as important as the next detail.
The money belongs to individuals who have never heard of these products, who do not know what an interval fund is, who will never see the valuation reports for these companies.
Every behavior in the market that would have created problems for these private funds is a behavior the 401(k) investor cannot perform.
That is not a flaw in the evergreen private funds’ design.
It is the design.
The money will arrive through paychecks every two weeks, regardless of whether the markets are up or down. These investors will not read market news. Every other Friday, the contributions show up.
From the perspective of the evergreen private fund manager, it is the most beautiful capital in the world.
The fear of litigation that has kept alternative investments out of 401(k) plans for decades will be dramatically reduced after the implementation of this Department of Labor proposal, which grants fiduciaries who follow its process a presumption of prudence.
The funds already exist.
The teams that will sell the investments have already been hired.
The partnerships have already been arranged.
“Democratization” is already in draft press releases and waiting for the Department of Labor to release the official rule number.
When the rule is released, the industry will have a story to tell that will practically write itself.
Retail investors are clamoring for access to evergreen private funds.
The industry built the infrastructure to satisfy the demand.
Washington finally opened the door.
Technically true.
Completely misleading.
Retail investors are not clamoring to invest in evergreen private funds. They have no idea these funds exist.
It is the giant investment companies inside the building who are clamoring for subscriptions to continue their efforts to raise capital.
Show me an industry that has depleted its source of capital. I will show you a regulatory push to open the next one.
Every time.
Nothing has changed in the industry. Not the fees. Not the visibility into the marks of the investments made by these funds. Not the liquidity of their private loans.
The only thing that has changed is where their next dollar of capital can be found.
None of this is illegal. Some of it may not even be wrong. Industries find new sources of capital all of the time.
Can we please retire the word “democratization” in connection with private evergreen funds?
Democratization means giving retail investors access to the same investments that the wealthiest investors in the world enjoy.
This is the wealthiest investors in the world gaining access to the money of retail investors.
This is not democratization.
It is refinancing.
The 401(k) plan is not the beneficiary of the development of evergreen private funds.
It is the solution to someone else’s capital problem.
Get Behind the Yield free by email. Short enough to read before your first meeting, specific enough to use in it. Subscribe here.
Need CE hours? Six self-study bond courses, accepted by CFP Board. See the courses.